Jassy: Bedrock could become as big as EC2; AWS grows 39% to $46 billion in Q3
🕒 Published on Zendoric: November 3, 2026 · 00:06
✨ AI-generated · how it's made
Amazon CEO Andy Jassy said on the fiscal third-quarter earnings call (for the quarter ended September 30) that Bedrock, AWS's AI inference service, could become as big as its core compute service, Elastic Compute Cloud (EC2).
📚 Go deeper
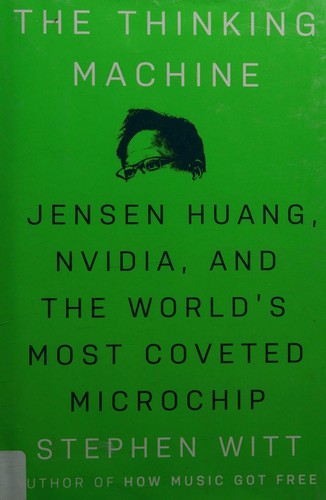
The story of NVIDIA and Jensen Huang: how a video-game card company ended up making the most coveted resource on the planet.
As an Amazon Associate, Zendoric earns from qualifying purchases; the price does not change for you. · all our recommended books →
Amazon CEO Andy Jassy said on the earnings call for the fiscal third quarter (ended September 30) that Bedrock, AWS's AI inference service, could become as big as its core compute service, Elastic Compute Cloud (EC2). His argument is that companies will adopt multiple models at once and will want to avoid being locked into a single provider, without giving up security, controls or the ability to switch models.
Jassy backed that thesis with his own experience: more than twenty years in technology have taught him, he said, "that there is no one tool to rule the world." He recalled that Google's TensorFlow was expected to be the dominant AI framework, yet today PyTorch is much larger. In his view, within two to three years six to eight models could cover at least 95% of workloads, with different models excelling at reasoning, coding, visual tasks, latency and cost. He added that most customers will use several models, many of them within a single generative AI application.
On Bedrock, he shared these figures: token volume grew almost 17-fold year over year, and spending by Fortune 500 customers rose almost sevenfold. He called it the fastest-growing multibillion-dollar service in AWS history. Tens of thousands of customers use Bedrock AgentCore, and twice as many agents were deployed in the third quarter as in the previous three quarters combined. Jassy also noted that the acquisition of DuckLabs will allow queries to run across AWS analytics services without migration or portability costs, that Lambda surpassed $1 billion in annualized revenue, and that more than 400 million customers used Alexa for Shopping over the past 12 months, with interactions nearly six times higher than the previous year.
According to Jassy, AWS benefits from a virtuous circle: customers put applications and data in its cloud, run inference close to that data, and then consume more compute, storage and networking for post-training, reinforcement learning and agent tooling. Inference accounts for "quite a bit more" than half of AWS's AI revenue, although companies are still early in using it at scale. He also took aim at "neoclouds": he said AWS's business model is superior to that of companies that mainly host GPUs or rent data center capacity on a short-term basis, and that using neoclouds means roughly 3,500 basis points worse operating margin compared with leasing data centers long-term. He said most of Amazon's capacity is owned or leased long-term.
As a sign of the cloud's potential, Jassy said around 85% of global IT spending is still on-premises, with a 10- to 20-year cycle for that share to move to the cloud. He said AWS has seen mainframes, storage networks and other workloads once thought immovable migrate.
On investment, Amazon is maintaining cash capital expenditure of around $220 billion in 2026 and "significantly more" in 2027. AWS installs an AI accelerator roughly every 14 seconds, and according to Jassy customers consume the capacity almost as fast as it is installed. The company has planned its capex for the next eight to ten quarters, with visibility into deals of hundreds of megawatts and gigawatts through 2029. Jassy argued that AI operating margins are improving "rapidly" and are "well ahead" of those of the traditional cloud at a comparable stage.
Custom silicon is another key piece. Revenue commitments for the Graviton CPU and the Trainium AI accelerator each grew more than 20-fold year over year, and the chip business grew at a triple-digit rate. Jassy credited Graviton with 30-40% better price-performance than other x86 providers, and noted that reinforcement post-training and agent tool use run mostly on CPUs. Custom silicon customers saved more than $2 billion in the quarter. AWS plans to offer its chips externally by the end of 2027 and is still weighing the trade-off between selling them and using them in its own cloud: selling generates revenue sooner, while using them internally for five or six years produces more absolute revenue and free cash flow. Jassy expects the cost of inference to keep falling, and suggested that AI-driven security (finding and fixing vulnerabilities at scale) could account for around 20% of tokens within one to two years. He also said he believes virtually every modern enterprise application in production will be rewritten to have agentic capabilities.
Financial results: AWS sales grew 39% year over year to $46 billion, for an annualized run rate of $184 billion, the sixth consecutive quarter of acceleration and the fastest growth in almost five years. The backlog grew at a triple-digit rate to $578 billion. AWS operating income was $17.8 billion (+56%). Amazon's net sales rose 13% excluding currency effects, to $201.9 billion, and operating income grew 61% to $28.1 billion. Net income fell about 2% to $20.7 billion, owing to a $9.5 billion pre-tax gain the previous year tied to its investment in Anthropic. Over the trailing twelve months, operating cash flow grew 29% to $168.3 billion, but there was a free cash outflow of $42.4 billion, compared with an inflow of $14.8 billion a year earlier, due to $94.8 billion more spent on property and equipment, mostly for AI.
AWS projects growth rates above 40% in 2027 and 2028 and expects to reach $1 trillion in revenue within five to ten years. Amazon will launch initial service of its Leo satellite internet network this year; CFO Brian Olsavsky said most of the costs will be expensed in the fourth quarter and will begin to be capitalized in the first quarter of next fiscal year. For the fourth quarter, Amazon expects net sales of $240 billion to $247 billion and operating income of $28.5 billion to $33.5 billion. After the market closed, the stock fell about 7% to around $226.
The article also notes, from the channel partners' perspective, that AWS has more than 140,000 partners worldwide according to CRN, and quotes a cloud services provider that attributes around 40% of its new work to the relationship between Oracle Cloud Infrastructure and AWS or other clouds. It should be noted that all figures and forecasts come from statements by Amazon's management on the earnings call.
📚 Go deeper
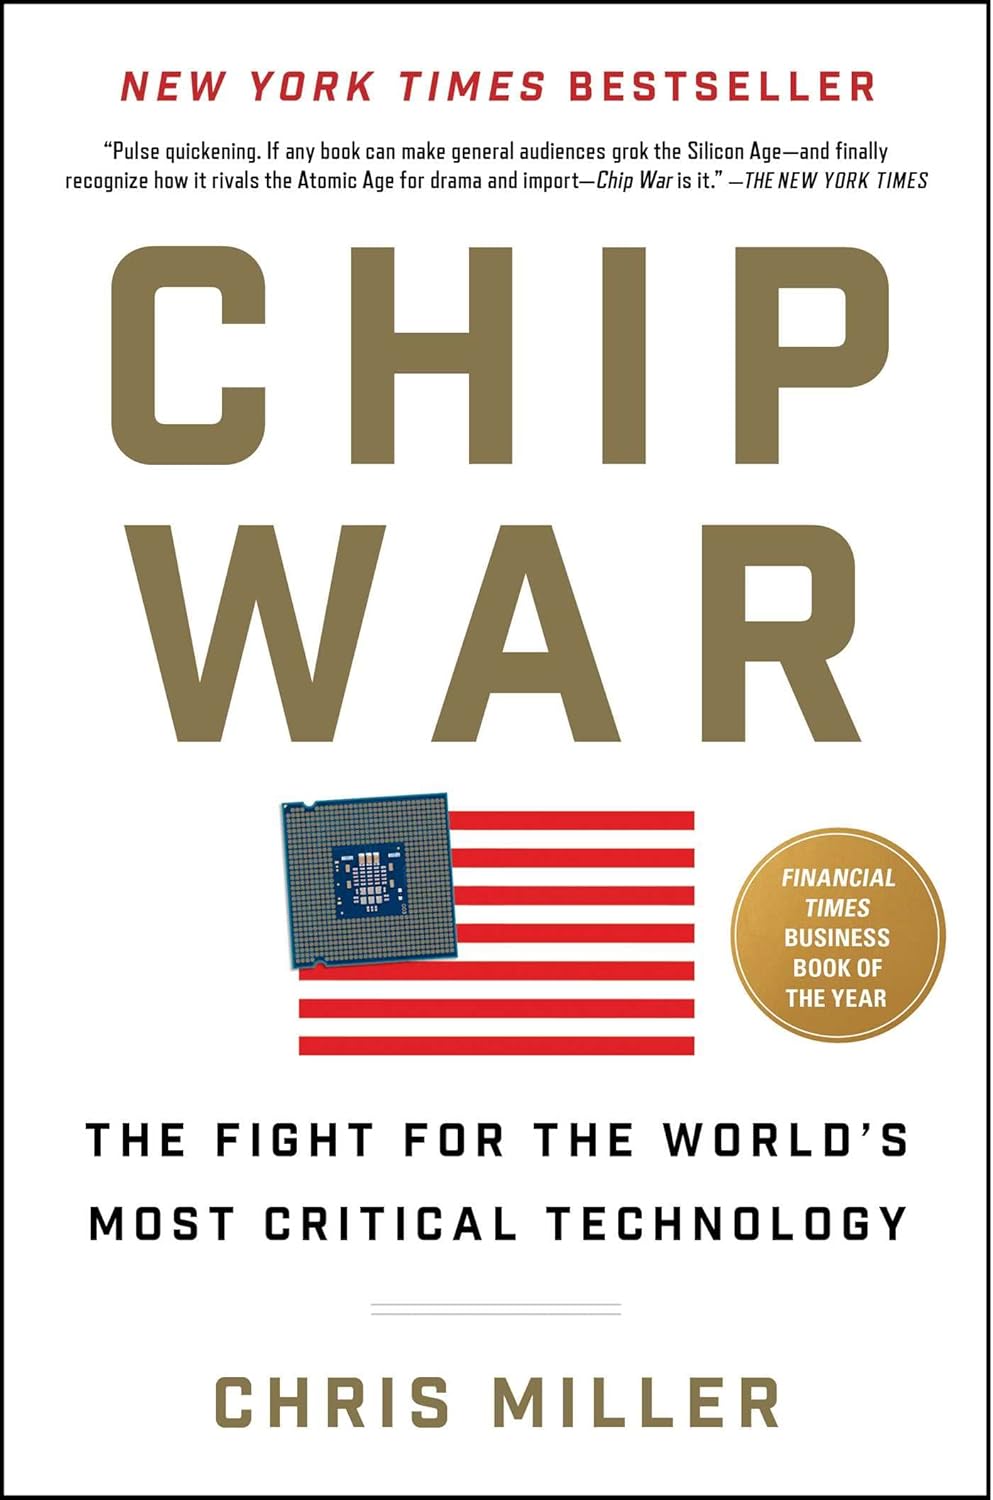
Semiconductors as the oil of the 21st century: history, espionage, and why an island of 23 million people underpins the entire AI economy.
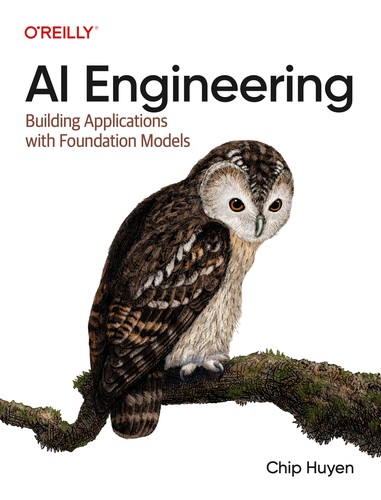
The reference manual for building products on top of AI models: prompts, RAG, fine-tuning, agents, evaluation and deployment.
As an Amazon Associate, Zendoric earns from qualifying purchases; the price does not change for you. · all our recommended books →
🔗 Related on Zendoric
- Meta prepares a cloud business to sell its excess AI compute capacity · 2026-07-03
- The US$1.8B contract between Anthropic and Akamai reveals where AI's next battle is being fought: infrastructure · 2026-07-04
- mlx-serve: frontier AI now fits on a Mac, with no cloud or subscription — the symptom of a deeper shift · 2026-07-04